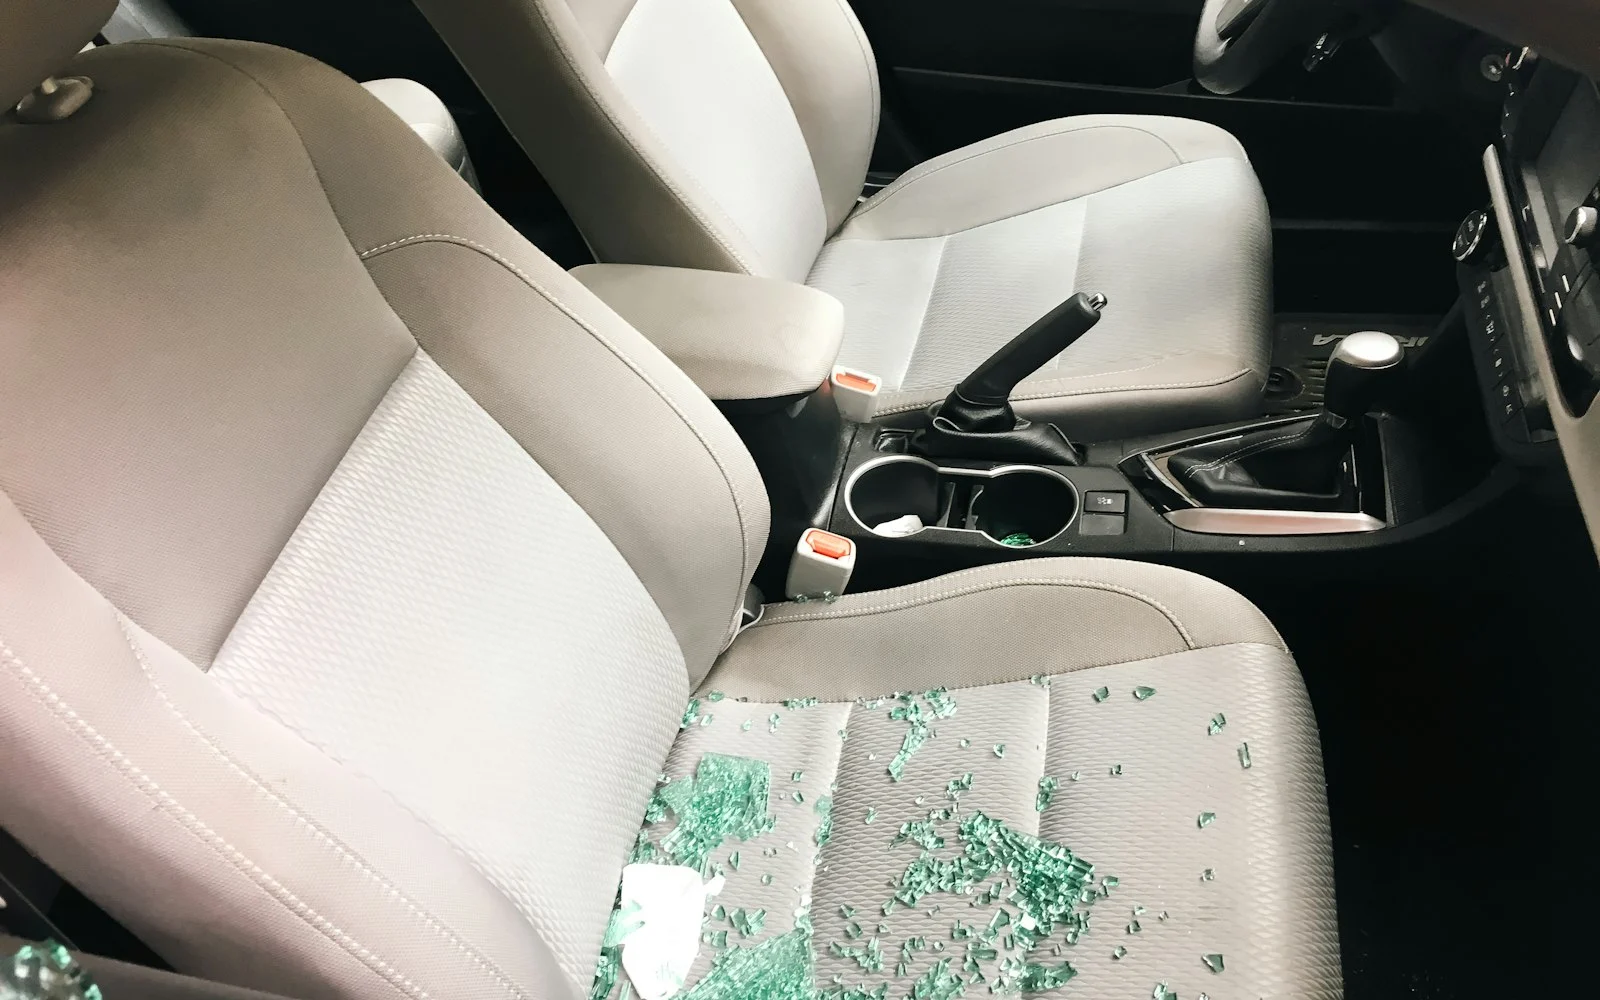
Forty minutes inside the store, maybe less. You picked up a coffee, found the last thing on the list and stood in a checkout line that wound back past the gift cards and the phone chargers. When you come back out to the lot off Tomball Parkway, the rear passenger window is a pile of little green-tinted cubes on the asphalt, and the shopping bags that were on the back seat are gone.
Now the surprise. You’re probably looking at two policies, not one. Auto pays to fix the car. Whatever got taken from inside usually goes to your homeowners or renters insurance instead, and each of those carries its own deductible, which changes the math a lot more than people figure.
Does car insurance cover a broken window from a break-in?
Yes, if you carry comprehensive. That’s the part of an auto policy for damage that doesn’t come from a collision, and a break-in is about as classic a comprehensive claim as there is. Smashed glass. A punched-out door lock. A steering column somebody tore apart trying to start the thing. Comprehensive also pays when the whole car disappears.
Carry liability only? Then none of that is covered, sorry. For a refresher on comprehensive, our post on hitting a deer in Texas explains it through a pretty different sort of claim, one with antlers.
Are personal items stolen from a car covered by auto insurance?
Generally, no. An auto policy covers the vehicle and the equipment bolted into it, like the factory sound system. Your stuff isn’t part of the car. The shopping bags, the laptop, your phone, the sunglasses clipped to the visor, the gym bag, the kids’ tablets. None of it.
Those things go to the personal property section of a homeowners or renters policy, which covers your belongings away from the house too, not only inside it. Different deductible, though. And many policies put lower special limits on theft of certain categories, with jewelry, cash and firearms near the top of that list. Our explainer on what a Texas homeowners policy covers shows where personal property fits.
Aftermarket gear is its own little wrinkle. That custom stereo, or the light bar on the roof? It may only be covered up to a limit unless you told your insurer about it.
Not your car? The split mostly holds anyway. Say your bag gets lifted from a rental in San Antonio over Thanksgiving, or out of a buddy’s truck while you’re inside at a Texans game. Your belongings still fall under your own home or renters policy, and the damage to the car goes to whoever insures the car.
How do two deductibles change a break-in claim?
Let’s run a hypothetical. The window costs $450 to replace. In the bags were $700 in gifts and a $1,300 laptop, so $2,000 in stolen property.
Your comprehensive deductible is $500. The window repair falls under it, so the auto policy pays nothing.
Your homeowners policy has a 1% deductible on a $280,000 dwelling limit, which works out to $2,800. The $2,000 in stolen items is under that too, so the home policy pays nothing either.
Total out of pocket: $2,450. And you were “fully insured” the whole time.
Tweak one thing, though. A renter with a $500 deductible on a renters policy might see a $1,500 payment on that same $2,000 theft. Or say the laptop was a $3,000 machine you own outright; suddenly the homeowners claim could be worth filing. Deductibles decide a lot of this, which is why we spend so long on them in our guide to choosing an auto insurance deductible in Texas.
What about a work laptop, tools or a gun?
Company laptop? That’s the employer’s insurance problem, not yours. Business property you own is trickier. A contractor’s drills and saws riding in the truck bed are often limited or excluded on a homeowners policy, especially away from the house, so tradespeople need business coverage for tools and equipment.
Then there are guns, which we get asked about more than you might think in this part of Texas. A homeowners policy usually has a sublimit for firearm theft, a fixed dollar cap that one good deer rifle with a scope can exceed on its own, unless the guns are scheduled separately. Keep the make, model and serial number of each one written down somewhere other than the truck, and call the police the same day if one goes missing, since a stolen gun report matters for more than the insurance claim.
What should you do after a car break-in?
Leave the glass where it is for a few minutes and call the police first. The non-emergency number is fine when the thief is long gone; Tomball PD takes it inside city limits, and outside them it’s usually the Harris County Sheriff’s Office or a constable precinct. Get the report number before you drive off, then take photos of the window, the glass on the seat and the parking space itself.
That evening, write out what was taken and dig up receipts, order confirmations or card statements for the bigger items. Cancel any cards that were in the car and change the passwords on a stolen laptop or tablet. If the house keys, the garage door opener or the registration with your address on it were in the glovebox, change the locks and reprogram the opener that same day. Then call us, and we’ll sort out which policy handles which part and whether either claim is worth filing.
How do you keep your car from being broken into during the holidays?
Thieves work shopping center lots in November and December for an obvious reason. They know what’s in the cars. Some just sit there and watch people load bags into the back seat, then wait for them to wander into the next store.
So put purchases in the trunk before you drive to your next stop, not after you park there. Don’t leave anything in sight, not even a charging cord or a phone mount, since those hint that a device is in the glovebox. Leave laptops and guns at home or carry them inside with you. Park under lights near the entrance when you can, lock up, and keep the key fob with you instead of in a cupholder.
None of this is foolproof. It just makes your car a less tempting choice than the one parked next to it.
Frequently asked questions
Is a stolen catalytic converter covered?
Usually, under comprehensive, because the converter is part of the car. Your comprehensive deductible applies. And if parts are back-ordered, expect to wait.
Does renters insurance cover items stolen from my car?
Generally, yes. Renters personal property coverage follows your stuff away from home, subject to the deductible and any special limits.
Will a break-in claim raise my car insurance?
Insurers tend to look at comprehensive claims differently from at-fault accidents. You didn’t cause the break-in, after all. Rating rules differ by company, though, and a string of claims of any kind can affect premiums.
What if my whole car is stolen with my stuff in it?
Then it’s two claims. Comprehensive for the car, homeowners or renters for what was inside. Call police right away either way.
What if my car is broken into in my own driveway?
The driveway doesn’t change anything. The broken glass is a comprehensive claim and the missing gym bag goes to your homeowners or renters policy, exactly as if it had happened at the mall. Plenty of overnight neighborhood break-ins involve unlocked cars and someone walking the block at 3 a.m. pulling on handles, so lock it even when it’s parked ten feet from your front door.
Want to check both sides of your coverage?
The easiest time to look at your comprehensive deductible and your home or renters deductible is before anything goes missing. Call Reid & Associates at (281) 716-5814, drop in at 703 Malone St. in Tomball, or send a quick message. Our auto insurance page has more on comprehensive and the other optional coverages.
General information only, not a coverage statement. Your auto and home or renters policies each have their own terms, limits, deductibles and exclusions, and those control. Availability varies.