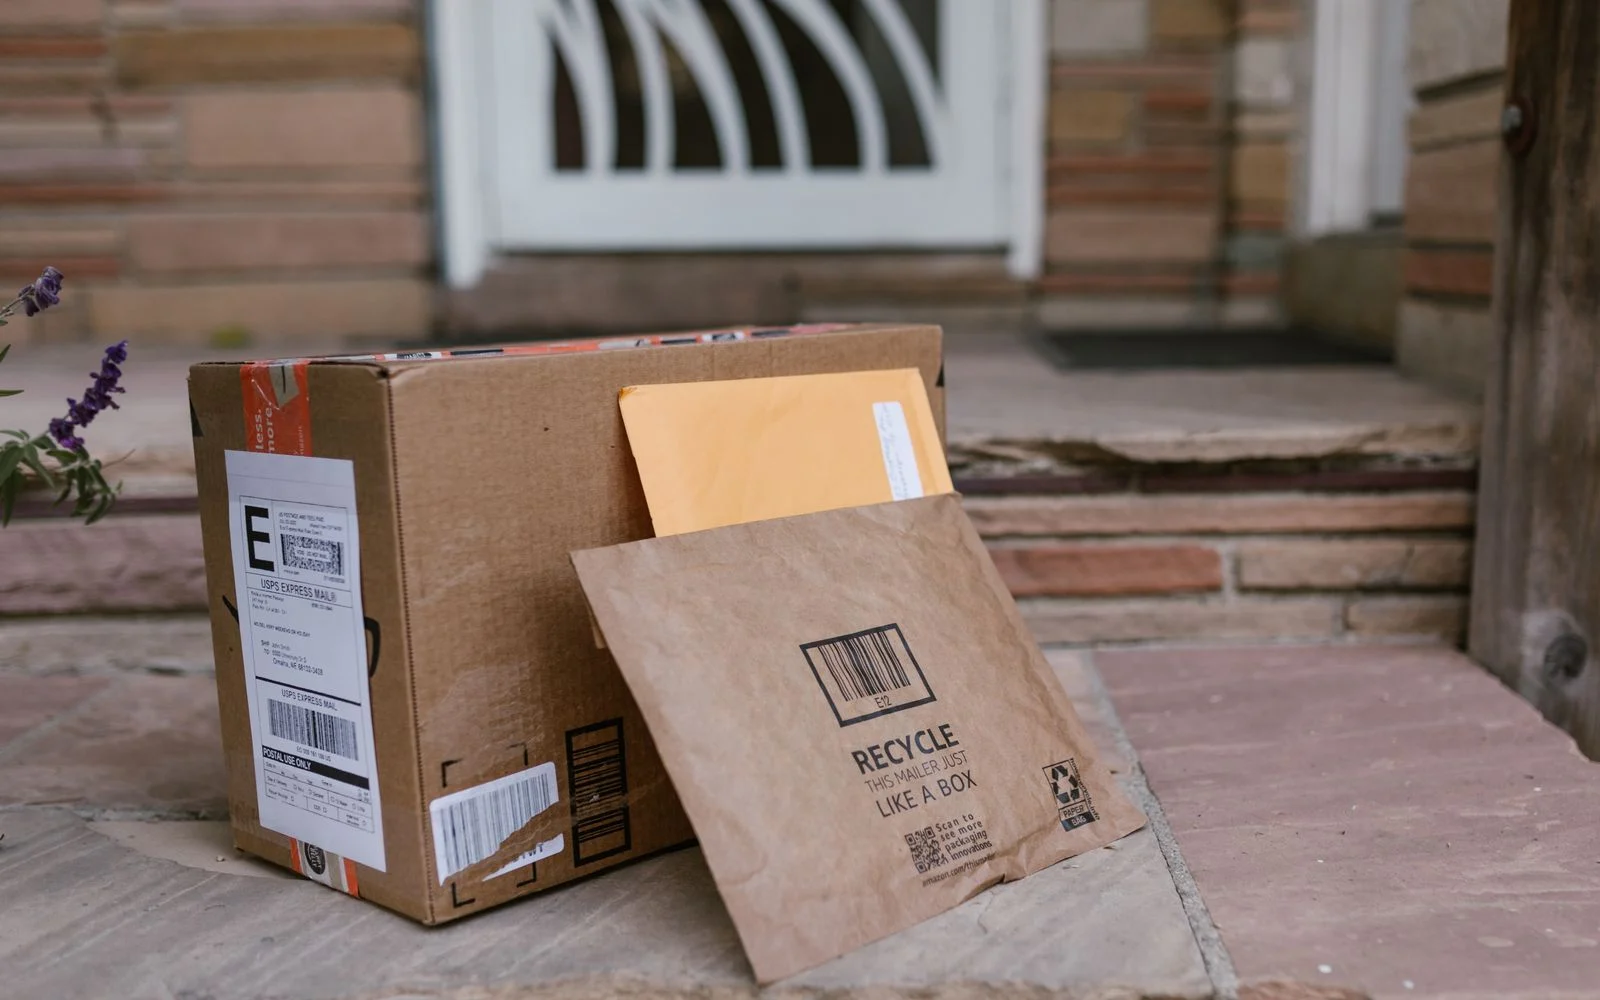
A box swiped off your porch counts as stolen personal property, the same as a bike taken out of the garage, so a homeowners or renters policy generally does cover it.
Very few of those claims get filed, though, and for a dull reason: the deductible. Most of what disappears off porches around here is small stuff, like a phone case or a few stocking stuffers from a midnight sale.
So the real fix for porch piracy starts with the retailer and the carrier, not your insurance company. Below is the order we’d go in, and when a claim is actually worth the trouble.
Does homeowners insurance cover packages stolen from my porch?
Yes, in most cases. Picture a pair of work boots landing on your doormat at 2:10 on a Wednesday, the driver snapping the delivery photo, and nothing but the mat left when you pull in at six. Those boots were yours the minute they hit the porch, so the theft goes against the personal property section of your homeowners or renters policy, the same as if someone walked off with the grill from your back patio (our guide to what a standard Texas homeowners policy covers has more on that section). Your regular theft deductible applies, and a box of jewelry could run into a lower special limit too.
A misdelivery is a different animal. When tracking shows the box went to a house on the next street, or it never left the warehouse, you never had it in the first place, and that’s for the seller and the carrier to sort out.
Why is a stolen package claim usually not worth filing?
Two reasons. Math, and history.
Math first. Say your homeowners deductible is $1,000. Somebody swipes a $150 sweater, and the policy pays nothing. A $600 pair of earbuds? Still nothing. And three boxes taken on three different days aren’t one claim. They’re separate thefts with separate deductibles, so you can’t stack them.
Then the history. Small theft claims still land in your claims history, and plenty of insurers check that history at renewal. Collect $200 over your deductible today and it could cost you more than that over the next few years. Or not. Depends on the company. Our article on why homeowners insurance goes up in Texas covers how claims history fits in with everything else.
What should you do first when a package is stolen?
Start with the people who sold it and shipped it. Not with us.
First, make sure it’s really gone. Walk around the side of the house. Look behind the planters, check the neighbors’ porch, text your teenager to ask if they grabbed it after school. You’d be amazed how often that’s the whole story.
If the search turns up nothing, the store gets the first crack at fixing it, well before we do. Find the drop-off photo in the order, and if it shows your own front door with the box propped against the storm door at 1:47 on a Tuesday, whoever picks up the retailer’s chat really doesn’t have much to argue with. Plenty of stores just reship it or refund you, and you never get anywhere near a deductible. We’d ping the carrier too, since a few of them will run a trace.
Then report it. Inside Tomball city limits that’s Tomball PD; in unincorporated Harris County it’s the sheriff’s office or your precinct constable, and up in south Montgomery County, outside city limits like Magnolia’s, it’s the Montgomery County Sheriff or a constable. Keep the report number next to your order and tracking numbers, because the retailer, your card company and possibly your insurer will each ask for it.
Check your credit card, too, since some cards include purchase protection against theft for a stretch after you buy something (read the terms before counting on it). Only after all that, and only if the loss is big, should you call us about a claim.
When does a stolen package claim make sense?
It has to be one theft, and a big one, before the numbers start to work. Picture a laptop for your daughter’s spring semester ($1,800) and noise-canceling headphones ($400) arriving on the same Tuesday afternoon and gone by the time anyone gets home at 5:30. That’s $2,200 out of a single theft. With a $1,000 deductible the claim could pay around $1,200, assuming the retailer won’t replace them and nothing in the policy limits the payment. All of those figures are invented, by the way.
Think TVs. A desktop computer. A whole stack of Christmas gifts swiped in one go. A lower deductible makes more of these thefts worth claiming, but small stuff almost never is.
On the fence? Call us before you file. That conversation’s free, and we can pull up your deductible and claims history together.
Do renters get the same coverage?
Pretty much. Renters personal property coverage treats theft the way a homeowners policy does, with its own deductible and limits. Live in an apartment off Kuykendahl? The complex’s insurance covers the building. Not your packages, even when they vanish from the mailroom or the package room downstairs.
Same logic with stuff taken from your car. Auto fixes the car, and your belongings land on home or renters coverage, which we got into in our post on items stolen from your car.
What about gifts you ship to someone else?
Gifts shipped to someone else are murkier. Say you ordered a stand mixer for your sister in Katy and it disappears off her porch two days before Christmas. You’re the buyer, so you’re the one who opens the claim with the store or the carrier, and that’s how the replacement normally happens. Which homeowners policy would respond, yours or hers, isn’t always clear-cut, and for a typical gift the deductible would eat the claim anyway.
If you’re shipping something valuable, buy the carrier’s declared-value coverage and ask for a signature at delivery. Those two steps solve more problems than an insurance claim ever will.
How can you stop porch pirates?
Porch thieves mostly go after boxes they can see from the street, and by mid-December a lot of porches in Spring and Cypress look like a small loading dock.
A video doorbell won’t stop all of them, but it puts some off, and a clip with a face and a timestamp is something police and the retailer can actually use. The delivery instructions box on most shopping accounts is underused. Ask for packages at the side door, behind the fence gate or on the back patio, out of the line of sight from the road. For an expensive order, require a signature.
Some people take the porch out of it completely. Shipping to the office works if your employer doesn’t mind boxes piling up at the front desk, and so do pickup lockers, in-store pickup or asking the carrier to hold packages at a local facility. In Magnolia or Rosehill, where the house might sit a few hundred feet back from a county road, a lockable parcel box near the front door is worth considering.
Frequently asked questions
Will the retailer replace a stolen package?
Most big retailers have a process for it, and the driver’s drop-off photo often decides how it goes. A photo of your porch with the box later missing is a theft; a photo of someone else’s door is a misdelivery, which is even easier for them to fix. Call the store before your insurer either way.
Is stealing a package a crime in Texas?
Yes, it’s theft under Texas law, and the charge depends mostly on the value of what was taken, so a $25 order and a $2,500 order are treated very differently. Report the small ones too. Police tie cases together when the same car turns up on three doorbell cameras on one street.
Does a security camera lower my homeowners insurance?
That’s up to the insurer and the device. Ask us which discounts apply to your policy before you buy one for that reason.
Are packages stolen while I’m traveling for the holidays covered?
A short trip doesn’t change your coverage. Still, a neighbor grabbing deliveries, or pausing shipments until you’re back from Grandma’s, beats filing a claim.
Can I file a claim for a package stolen from my mailbox?
It’s handled about the same way as a porch theft: personal property, subject to your deductible. Report mail theft to the post office and local police as well.
Not sure what your deductible is?
That’s the number to know before the holiday deliveries start piling up. Give Reid & Associates a call at (281) 716-5814, come see us at 703 Malone St. in Tomball, or ask us online. We can walk through your homeowners insurance or renters coverage in a few minutes.
This article is for general information and isn’t a statement of coverage. Policy terms, limits, deductibles and exclusions control every claim, and coverage options vary.